Paperback
ISBN 979-8-9967976-1-5

The real version, not the pitch deck.
Available Wednesday, November 4, 2026
Somewhere recently, a friend or a wealthy relative mentioned they're "an LP" in a venture fund. You nodded. You didn't ask what that meant, what they actually own, or when they get their money back.
Venture capital has built some of the largest fortunes in modern finance. It hasn't built an instruction manual for the people funding it. Founders get accelerators and pitch coaches. Fund managers get conferences and trade press. The limited partners, the family offices, the angel investors leveling up, the executives with an unsigned subscription document sitting in their inbox, get almost nothing. They're expected to just know.
LP answers those conversations: what a fund actually is, how fees and carried interest decide who really profits, how to size up a manager before handing them a decade of your capital, and what the GP relationship looks like once the numbers aren't what anyone hoped. None of it assumes you've done this before. All of it assumes you want the real version, not the pitch deck.
The first investment Brian made that changed how he thinks about money turned every dollar into thirty-three in under two years, and what followed was a decade of sitting on both sides of the table that no book had been written to explain.
Most of the value creation in the companies that reshaped the economy happened before anyone could buy the stock, and this chapter explains exactly why.
The honest case: venture doesn't automatically beat public markets, manager selection is basically the whole game, and the data on what top-quartile funds have actually returned makes the argument better than any pitch would.
LPs, GPs, SPVs, QPs, capital calls, carry: the structural vocabulary of the asset class explained plainly so the rest of the book makes sense.
IRR, TVPI, DPI, and MOIC each measure something real and can each be made to look better than reality, and this chapter shows you how to tell the difference.
A fund document isn't a legal formality, it's an incentive system that runs for a decade whether you understand it or not.
What experienced LPs are actually evaluating when they sit across from a GP, from character and team stability to what failure stories reveal about someone's judgment.
A fund's sourcing engine is the hardest thing to fake and the most determinative of long-term performance, and this chapter explains how to evaluate whether it's real.
What the investment decision process looks like from the inside, and what that process reveals about the fund's actual discipline versus its marketing.
Operational due diligence, the part that sounds boring until a fund unravels over bad bookkeeping and a GP who never hired a real administrator.
The full LP diligence process in the sequence that actually works: reference calls, data rooms, behavioral signals, and bias controls that prevent you from confirming a decision instead of testing it.
The shift from fund-picker to long-term steward: what it means, why it changes your decisions, and how your reputation in a relationship-driven industry compounds over time.
How to build a portfolio of funds that survives the J-curve, captures the power law, and doesn't require you to be right about any single manager.
LP-GP partnerships that last a decade develop under pressure, and this chapter covers what makes them hold through hard markets and what breaks them.
What to do when you need cash and your capital is locked, how the secondary market for LP interests works, and what continuation funds reveal about everyone involved.
The pre-commitment checklist, how to find your first fund without waiting to be found, and why the investors who get genuinely good at this are the ones who stayed in long enough to let the evidence update their thinking.
Out Wednesday, November 4, 2026. Pick your format.
ISBN 979-8-9967976-1-5
Coming later
Includes a short foreword by David Meerman Scott, bestselling author of The New Rules of Marketing and PR and Fanocracy.
“There's nothing like real-world experience and tremendous success when it comes to truly passing along information. Brian has both, and this book can save anyone interested in investing in venture capital funds a lot of time and money.”
“I saw myself in Sarah's story. I sold my company and wanted to invest in early-stage technology, but there was no blueprint, just years of trial and error. This is the book I wish I'd had when I started.”
“What you are holding is not a sales pitch for venture capital. Brian is honest about the costs in a way that surprised me... This is the book I wish I had owned the day I took that little slice of equity and had no idea what I was holding.”
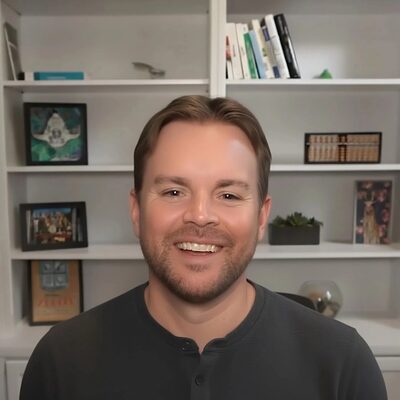
Brian Robert Bell has spent his career on the LP side of the table. He runs a venture fund, he's an LP in several others, and as host of the Ignite Podcast, he's asked hundreds of investors and allocators the questions everyone else was too polite to ask on the record.
He is Managing Partner of Team Ignite Ventures.
Get a note the day the book is out, plus the Ignite Insights newsletter: Ignite Podcast interviews with founders and investors, the weekly Last Week Ignite market digest, and essays on venture, AI and fundraising.